MTD for Landlords: How Making Tax Digital Applies to Rental Income
Table of Contents
In short: HMRC's Making Tax Digital for Income Tax applies to UK landlords on exactly the same rules as the self-employed. Your gross rental income, before repairs, letting agent fees or mortgage interest, is added to any self-employment income, and over £50,000 in 2024-25 means MTD from 6 April 2026. The threshold falls to £30,000 from April 2027 and £20,000 from April 2028.
If you rent out property in the UK, it's easy to assume Making Tax Digital is a sole trader problem that doesn't apply to you. It isn't. MTD for landlords runs on exactly the same rules as MTD for the self-employed. Your rental income counts toward the same thresholds, on the same start dates, with the same quarterly updates. This guide covers how property income is assessed, what happens if you also have a job or a business on the side, and what records you'll actually need to keep once you're in scope.
Disclaimer: This article provides general information only and does not constitute tax advice. Consult a qualified accountant or tax adviser about your circumstances.
MTD for Landlords: The Same Rules, Same Thresholds
Making Tax Digital for Income Tax applies to anyone registered for Self Assessment with self-employment income, property income, or both. Landlords aren't a special case, and there's no separate "landlord threshold." The same qualifying income bands and start dates apply:
- Over £50,000 in the 2024-25 tax year: MTD from 6 April 2026
- Over £30,000 in 2025-26: MTD from 6 April 2027
- Over £20,000 in 2026-27: MTD from 6 April 2028
HMRC expects around 2.9 million sole traders and landlords to be in scope by 2028. If you're a landlord with a decent-sized portfolio, or even a single higher-value let, you can hit these thresholds faster than you'd expect, because of how "qualifying income" is actually calculated.
How Rental Income Counts Toward Your Qualifying Income
The number that matters for MTD is your gross rental income before you deduct anything, not your rental profit. Repairs, letting agent fees, insurance, mortgage interest, ground rent: none of that comes off before you check it against the threshold. It's turnover, not the number that ends up on your tax bill.
That distinction catches people out. A landlord charging £3,200 a month across a couple of properties is already at over £38,000 a year in gross rent, regardless of how much of that gets absorbed by costs. Their taxable profit might be a fraction of that, but their qualifying income, for MTD purposes, is the gross figure.
Combining Property and Self-Employment Income
If you're a landlord who's also self-employed (freelancing, running a trade, consulting), HMRC adds your gross property income and your gross self-employment income together to work out whether you cross a threshold. Neither source has to clear £50,000 on its own.
For example, £28,000 in freelance income plus £25,000 in gross rents adds up to £53,000. That's over the April 2026 threshold, even though neither figure alone would trigger it. This is one of the most common ways landlords end up mandated earlier than they expected. For the full mechanics of how combined income is assessed, see our guide to sole trader and landlord combined income under MTD and how qualifying income is calculated.
Jointly-Owned Property: Only Your Share Counts
If you own a property jointly (with a spouse, a partner, or a family member), only your share of the rental income counts toward your own qualifying income, not the total rent collected on the property. Two joint owners splitting a rental income of £44,000 each report their own share against their own threshold, rather than either of them being assessed on the full amount. If you're unsure how your share is determined, that's a question for your accountant or HMRC directly, since it depends on how the property and any income-sharing arrangement are set up.
Quarterly Updates for Landlords
Once you're in scope, the reporting rhythm is the same four-times-a-year cycle as everyone else under MTD. Each update is cumulative, covering everything from 6 April to the end of that period, and due on a fixed schedule:
| Period covered | Deadline |
|---|---|
| 6 Apr to 5 Jul | 7 August |
| 6 Apr to 5 Oct | 7 November |
| 6 Apr to 5 Jan | 7 February |
| 6 Apr to 5 Apr | 7 May (following tax year) |
If you have both a property business and a self-employment business, MTD treats them as separate income sources for reporting purposes, so you'll typically be sending a quarterly update for your property income and another for your self-employment income, each covering the same period. And critically, nil updates are mandatory: if a quarter had no rental income or expenses in it, you still need to submit an update saying so. For the full deadline breakdown, see MTD quarterly update deadlines for 2026-27 and what actually goes in a quarterly update.
What Records Landlords Need to Keep
MTD quarterly updates want category totals, not a shoebox of paperwork, but you can only produce accurate totals if the underlying records exist. For most landlords, that means keeping a running record of:
- Repairs and maintenance: call-outs, materials, contractor invoices
- Letting agent fees and commission: management fees, tenant-find fees, renewal fees
- Landlord insurance: buildings, contents, rent guarantee
- Safety and compliance costs: gas safety certificates, EICR checks, EPC assessments
- Ground rent and service charges, where applicable
- Mortgage interest: this is treated differently for tax purposes than most other landlord costs, and the rules have shifted over the past few years. Keep a clear record of what you've paid, but check the current treatment with your accountant or gov.uk rather than assuming it's a straightforward deduction.
How a Receipt App Fits for Property Expenses
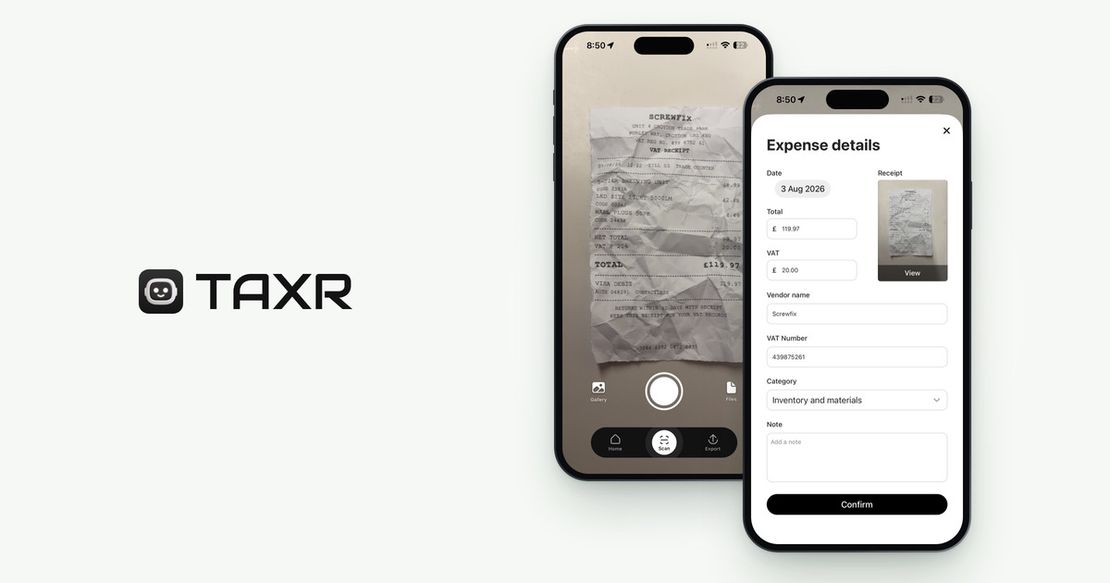
Landlord expenses tend to arrive scattered: an invoice by email from the letting agent, a paper receipt from a contractor, a card payment for a gas safety certificate. None of it naturally lives in one place, which is exactly the problem when you need a clean category total four times a year. Taxr isn't MTD software and won't file your quarterly updates. Think of it as the expense records underneath: photograph each paper receipt, or import an emailed invoice as a PDF, as it happens, and Taxr's AI reads the vendor, date, total, and VAT, then suggests a category for you to confirm. Taxr's UK categories follow the self-employment pages of the tax return, not the property pages, so for rental costs pick the closest match or add your own category (such as letting agent fees), and use the note field for the property. Export the records as Excel or PDF for your accountant, who can match them to the property expense categories. If you file yourself, check whether your MTD software can import the Excel file: HMRC lets you keep records and file in separate software only if they're connected by a digital link, such as a file import, and retyping the figures doesn't count.
If you're not sure which wave you fall into yet, our free MTD threshold checker tells you in seconds based on your gross income. And if 2026-27 is your first year in MTD, the first-year record-keeping checklist is a good next stop.
Get Your Property Records in Order for MTD
With one buy-to-let or a growing portfolio, the record-keeping habit is the same: capture each expense as it happens, keep it categorised, and you'll never be scrambling to reconstruct a quarter from memory. Download Taxr free and start building digital expense records today.