CIS Subcontractor Records and Making Tax Digital: What Tradespeople Need to Know
Table of Contents
In short: For HMRC's Making Tax Digital, a CIS subcontractor is a sole trader like any other: gross contracting income, before CIS deductions, counts towards the same thresholds, so over £50,000 in 2024-25 means MTD from 6 April 2026. Once in scope, you keep digital records of materials, tools, van and fuel costs and send HMRC quarterly category totals.
If you work under the Construction Industry Scheme (as an electrician, plasterer, plumber, roofer or any other trade paid by a contractor), it's tempting to assume CIS and MTD are two separate systems that don't overlap. They're not unrelated. Good CIS subcontractor records are exactly what Making Tax Digital expects from you, because underneath the CIS deductions, you're still a self-employed sole trader reporting your own income and expenses to HMRC. This guide explains how the two systems sit alongside each other and what you need to keep track of.
Disclaimer: This article provides general information only and does not constitute tax advice. Consult a qualified accountant or tax adviser about your circumstances.
CIS Subcontractor Records: Why MTD Still Applies to You
Being paid under CIS doesn't put you in a different tax category. For MTD purposes, you're a sole trader like any other, and the same qualifying income thresholds and start dates apply to you. Qualifying income is your gross self-employment turnover plus any property income, before expenses:
- Over £50,000 in 2024-25: MTD from 6 April 2026
- Over £30,000 in 2025-26: MTD from 6 April 2027
- Over £20,000 in 2026-27: MTD from 6 April 2028
If your gross income from contracting work, before any CIS deductions come off, crosses one of these thresholds, you're mandated into MTD on the matching date, exactly like a freelancer or a shop owner would be.
How CIS Deductions Fit Alongside MTD
CIS and MTD are solving different problems. CIS is a payment mechanism: when a contractor pays you, they deduct tax at your applicable rate before the money reaches you, and give you a payment and deduction statement for the transaction. That's been true for years and MTD doesn't change it.
MTD is a reporting mechanism: it's about how often, and how digitally, you tell HMRC what your business earned and spent. Your CIS deductions are effectively tax paid in advance, and they get reconciled at the end of the year against what you actually owe. The two systems meet at your tax return, but day to day, you keep doing what you've always done with your payment and deduction statements. For the exact mechanics of how CIS deductions are reconciled, gov.uk's CIS guidance is the authority; this article focuses on the MTD side.
What Goes in Your Quarterly Update
Once you're in scope, you submit four cumulative updates a year, each covering everything from 6 April to the end of that period:
| Period covered | Deadline |
|---|---|
| 6 Apr to 5 Jul | 7 August |
| 6 Apr to 5 Oct | 7 November |
| 6 Apr to 5 Jan | 7 February |
| 6 Apr to 5 Apr | 7 May (following tax year) |
Each update is a set of category totals: income from your contracts, and expenses grouped into categories like materials, tools, vehicle costs and subsistence. HMRC doesn't want individual receipts in the update itself; it wants the totals, which only come out right if the underlying records were kept properly through the quarter. And a quiet quarter doesn't get you out of it: nil updates are mandatory even if you didn't earn or spend anything in that period. For the full breakdown of what a quarterly update actually contains, see what goes in a quarterly update.
The Records MTD Assumes You're Already Keeping
This is the part that should feel familiar rather than new. MTD's category-total model maps almost exactly onto the receipts a tradesperson already generates every week:
- Materials: timber, plumbing parts, electrical supplies, cement, fixings, from the builders' merchant or trade counter
- Tools and small equipment: replacements, upgrades, consumables like blades and drill bits
- PPE: hi-vis, boots, gloves, hard hats, safety glasses
- Van and fuel costs: fuel receipts, servicing, repairs, parking
- Subsistence: food and drink on longer jobs away from your normal base, where allowable
None of this is a new category MTD invented. It's the same expense breakdown that's always gone into your Self Assessment return. The difference is that it now needs to be current every quarter, not reconstructed once a year.
Building the Habit: Van, Fuel, Tools, PPE
The reason trades lose more receipts than most is entirely physical: thermal paper fades, receipts live in a van door pocket or a jacket that goes through the wash, and a site with mud, rain, and a dozen jobs on the go isn't a filing system. The fix is capturing the receipt the moment you're handed it at the merchant counter, not at the end of the week when half of them have gone missing or illegible.
The quarterly rhythm actually suits how most trades already think about their business. Materials float, slower winter months, invoicing gaps while waiting on a contractor to pay: these are cashflow checkpoints you're probably already tracking informally. MTD just asks you to formalise the record behind them four times a year instead of once.
It's also worth knowing that if you're mandated from April 2026, you get some breathing room: there are no penalty points for late quarterly updates in your first year (2026-27). Late tax returns and late payments are still penalised, so it's not a free pass across the board, but it's a genuine window to get the habit right before it starts counting. Our guide to penalty points explained covers how the points system works once that grace period ends.
How Taxr Fits for Trades
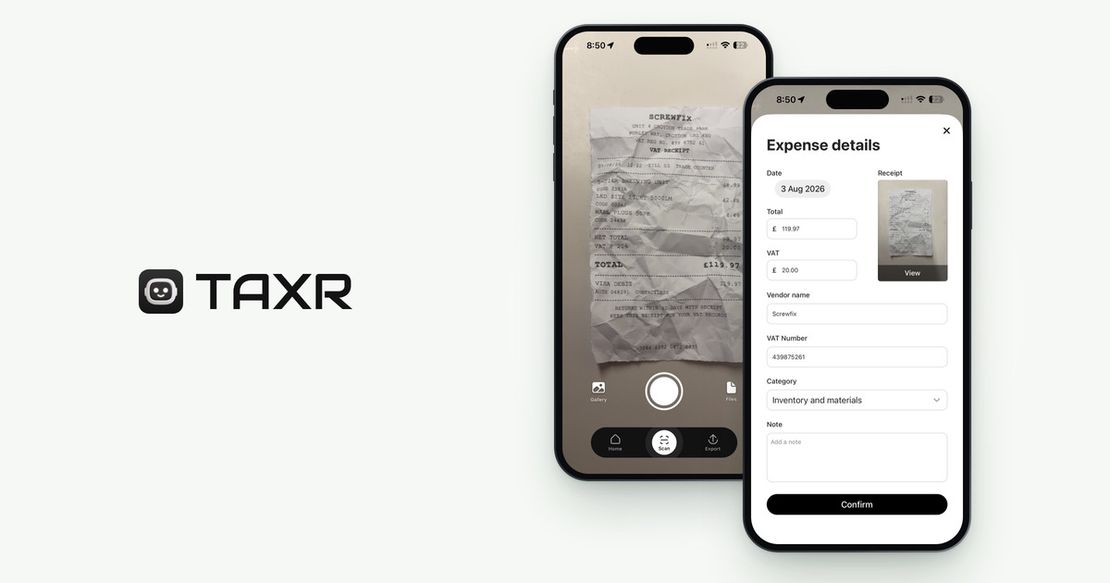
Taxr isn't MTD software and it doesn't file anything with HMRC. It keeps the expense records that sit underneath whatever you use to file. Photograph the receipt at the merchant counter, and Taxr's AI reads the vendor, date, total and VAT, then suggests a category from its UK set (materials go under cost of goods sold, tools under equipment, van costs under vehicle expenses or fuel), which you confirm. At the end of each quarter, export your totals as Excel or PDF and hand them to your accountant. If you file yourself, check whether your MTD-compatible software can import the Excel file: HMRC allows record-keeping and filing to happen in separate products only if they're digitally linked, and downloading and uploading a file counts, while copying and pasting doesn't.
For a broader look at what's allowable, see our guide to UK sole trader allowable expenses, and if 2026-27 is your first year in MTD, the first-year record-keeping checklist walks through getting set up.
Keep the Receipts, Skip the Shoebox
CIS already means most of your tax is deducted before you see it. Don't let the records side of the job become the part that catches you out. Snap materials and van receipts as you go, and quarterly updates become a quick export instead of a scramble through a van door pocket. Download Taxr free and start keeping trade-ready records from your next job.