What the 2026 Budget Means for IT Contractors
Table of Contents
In short: For Australian IT contractors, the 12 May 2026 Federal Budget made the $20,000 instant asset write-off permanent (now law) and brought back loss carry-back for Pty Ltd companies under $1 billion turnover. Payday super applies from 1 July 2026 if your company pays you a director's salary. The $1,000 flat deduction covers only wage or director income, not PSI.
If you contract software development, infrastructure, security, data, or any other IT discipline in Australia, here is what the federal budget 2026 IT contractors need to know from the 12 May 2026 Budget: what changes for your tax position, what stays the same, and what you should do now. Unlike a general Budget summary, this post focuses on the handful of measures that have a direct, practical impact on how IT contractors structure their work, purchase equipment, and plan their income. For a broader picture of what you can already claim, see our guide on tax deductions for IT contractors in Australia.
Disclaimer: This article provides general information only and does not constitute tax advice. Tax rules are complex and individual circumstances vary. Consult a registered tax agent for advice specific to your situation, and verify all Budget measures against the Budget Paper No. 2 and final legislation before acting.
Three Changes That Matter Most for IT Contractors
Two Budget measures and one earlier law will have the most direct bearing on IT contractors before the next lodgement deadline. First, the Instant Asset Write-Off (IAWO) is now permanent at the $20,000 threshold, so there's no more annual guessing about whether it will be renewed. Second, loss carry-back has been reintroduced for incorporated contractors under $1 billion turnover, letting Pty Ltd companies offset a current-year loss against tax already paid in the previous two years. Third, payday super (legislated in 2025, not part of this Budget) came into force on 1 July 2026, and if your contracting company pays you a director's salary, that obligation falls on you every payday, not at the end of the quarter. Each of these is worth understanding in detail.
Permanent IAWO: Hardware Refresh Cycles Without Annual Anxiety
The most practically useful change for IT contractors is the permanent designation of the $20,000 Instant Asset Write-Off. Previously, this threshold was renewed year-by-year, creating uncertainty about whether to accelerate a hardware purchase before a sunset date or wait until the next renewal was confirmed. That uncertainty is gone: the permanent threshold became law in 2026.
For the 2026-27 financial year and beyond, eligible small businesses (including sole traders and Pty Ltd companies under the $10 million turnover threshold) can immediately deduct the full cost of any individual asset under $20,000 in the year it is first used or installed ready for use, rather than depreciating it over its effective life. For IT contractors, the assets that comfortably sit under this threshold include laptops, external monitors, networking gear, NAS devices, development boards, webcams, ergonomic peripherals, and most server hardware bought for a home lab or development environment.
What falls outside the immediate write-off: high-end workstations configured for machine learning or video rendering that push past $20,000, multi-GPU rigs, and enterprise storage arrays. Those assets go into the small business depreciation pool at 15% in year one and 30% in subsequent years. If you are building a compute-intensive development environment, it is worth checking individual component costs: buying separate items each under $20,000 rather than a single bundled purchase may allow immediate deduction of each one, but get advice on whether the ATO would treat them as a single asset.
The permanent status matters for planning. You can now build a three-year hardware refresh cycle with confidence that the write-off will be available when each cohort of equipment is replaced. Full details on the measure are in our dedicated post on the permanent $20,000 Instant Asset Write-Off.
Loss Carry-Back: Only If Incorporated
If you operate through a Pty Ltd company with under $1 billion in aggregated annual turnover, the reintroduced loss carry-back lets you offset a tax loss in the current year against tax already paid in either or both of the previous two years, limited by your franking account balance. In practice, this means the ATO refunds some of the company tax you previously paid rather than forcing you to carry the loss forward to offset future profits.
For IT contractors, this is most relevant if your company had a lean year (perhaps a contract ended and you spent time on business development, or you invested heavily in tooling that reduced profit) while the prior year or two were strong. Instead of waiting years to absorb the loss through future income, you can receive a tax offset in your current year assessment.
The critical word is "incorporated." This measure is available only to companies. Sole traders, partnerships, and trusts cannot access loss carry-back; losses for those structures still carry forward under normal rules. Full detail on eligibility, the cap on the offset amount, and how to claim is in our companion post on loss carry-back for Australian companies.
If you are a sole trader generating over $120,000 consistently, this measure is one more reason to model the sole-trader-versus-company question with your accountant. Our sole trader vs company guide sets out the full comparison. The new loss carry-back tips the balance slightly further toward incorporation for higher-earning contractors with income variability.
Payday Super: Affects Single-Person Companies Drawing a Wage
From 1 July 2026, superannuation must be paid at the same time as wages, not quarterly as under the old rules, and it has to reach the fund within 7 business days of payday. This applies to any employer, including a one-person Pty Ltd company where the sole director also draws a salary.
If your contracting structure involves paying yourself a director's wage from the company (common for directors who want to access concessional super contributions or simply want a predictable personal income), payday super requires that the super component be transferred to your fund with each pay run. Running your payroll software quarterly and backdating super will no longer comply.
The practical implications: your payroll software needs to support same-day or near-same-day super payments, and your cash flow planning must account for super being a current payment rather than a deferred quarterly liability. For contractors on irregular contract income, this may mean keeping a larger float in the company account to cover super on payroll days even when client payments haven't landed yet.
Solo directors who take only dividends and no director's salary are unaffected: dividends are not salary or wages, and super obligations attach to salary. However, the trade-offs around salary versus dividend structuring are outside the scope of this post; run the numbers with your accountant. Full implementation detail is in our payday super guide.
ATO PSI Focus Continues
The ATO is part-way through $75.7 million of funding over four years from 1 July 2025 for its Personal Income Tax Compliance Program, set in the 2025-26 Budget rather than this one. It is a broad funding line, but IT contractors are a natural focus given the ATO's consistent signals about Personal Services Income (PSI) misclassification.
PSI rules themselves are unchanged. If your contracting income qualifies as PSI (because it is substantially the product of your personal skills and effort rather than the use of assets or a business structure), you are restricted to deductions that an employee could claim. This means the generous business deduction regime does not fully apply, and income splitting through a company or trust is limited.
The PSI tests remain as before: the results test, the 80% rule (whether 80% or more of your PSI comes from a single client), the unrelated clients test, the employment test and the business premises test. IT contractors on long-running single-client engagements, particularly those placed by an agency into what is functionally an employee role, are the profile the ATO continues to scrutinise. If your client mix or working arrangements have changed since you last assessed your PSI status, the ATO's continued compliance funding makes this a good time to reassess.
$1,000 Flat Deduction: When It Helps Contractors
The $1,000 flat deduction introduced in this Budget applies to work-related expenses against labour income: salary and wages, director fees and similar PAYG payments. It is not a business deduction for sole traders. The ATO applies it automatically in the individual's return, and any work-related expenses you claim reduce it dollar for dollar.
For IT contractors, it is relevant in two scenarios. First, if you run your contracting through a company and pay yourself a salary or director fees, that is labour income, so the $1,000 applies to it automatically. PSI you earn as a sole trader, or that is attributed to you from a company or trust, is not labour income, so the $1,000 doesn't apply to it. Second, if you have any salaried employment alongside your contracting (say, a part-time employee role plus an ABN contracting engagement), the flat deduction applies to the employee portion of your income.
Contractors operating as genuine businesses claim deductions on the business schedule. Those deductions are separate from the $1,000 flat deduction and don't reduce it, so claim them in full: IT contractors typically incur a wide range of hardware, software and professional development costs. More on when the flat amount wins is in our detailed comparison post on flat $1,000 versus itemising your deductions.
Trust Restructure Window: If You Use a Discretionary Trust
If your IT contracting income flows through a discretionary (family) trust, the 2026 Budget announced a measure that deserves attention even though it does not bite until 1 July 2028: a 30% minimum tax on the taxable income of discretionary trusts. It is not yet law; Treasury released exposure draft legislation in September 2026.
The intent is to prevent high-income earners from distributing trust income to beneficiaries on lower marginal rates, a strategy some IT contractors have used to reduce the household tax bill. From 2028, regardless of the recipient's marginal rate, trust income will attract a minimum 30% tax, paid by the trustee, with non-refundable credits for individual beneficiaries.
The window matters. A three-year rollover-relief period opens on 1 July 2027, allowing contractors to restructure out of a trust into a more appropriate vehicle without an immediate capital gains tax bill, but you need to plan now to be ready to act in the 2027-28 year. Full detail and restructuring considerations are in our post on the discretionary trust 30% minimum tax.
What Hasn't Changed for IT Contractors
Not everything moved. The GST registration threshold stays at $75,000, and most IT contractors are well above this and should already be registered. The Budget didn't change the working-from-home fixed rate (70 cents per hour for 2025-26), which is still the simplest way to claim home-office running costs without the record-keeping burden of the actual cost method. The vehicle cents-per-kilometre rate is 88 cents for FY2025-26 and 91 cents for FY2026-27, relevant if you drive to client sites or data centres. PSI rules, as noted above, are structurally unchanged. Standard equipment depreciation pools continue for assets costing $20,000 or more. None of these require any change to your current approach.
7-Step Action List for IT Contractors
Time your next hardware refresh for FY2026-27. Permanent IAWO means there is no advantage to rushing, but if you have been deferring a laptop or monitor upgrade, this financial year is as good as any, and the deduction is certain now that the permanent write-off is law. Check out our sole trader tax calculator to model the impact on your taxable income.
If incorporated, audit the prior two years' company tax paid. Confirm whether your company has a loss that can be carried back, and how much tax was paid in prior years that could generate an offset. Your accountant needs this before lodgement.
If you draw a director's salary, audit your payroll software now. Payday super from 1 July 2026 means your payroll run must include the super transfer. Check that your payroll platform (Xero, MYOB, QuickBooks or another) supports it in the version you use.
Review your structure given the full package. Loss carry-back for companies, the proposed trust minimum tax from 2028, payday super for directors: each change individually is modest, but together they shift the relative attractiveness of sole trader, company, and trust structures. See our guide to structures or visit the for sole traders page to understand your options.
Re-test your PSI status. Has your client mix changed? Are you still passing the results test or the unrelated clients test? With ATO compliance funding still flowing, a fresh assessment is worth the time, or ask your accountant to do it.
Decide flat $1,000 versus itemise for any wage or director income. The $1,000 applies to that income automatically; if you also have PSI or genuine business income, work through which deduction rules apply to each.
Book your accountant before the EOFY rush. The 1 July payday super start date, IAWO planning, and potential loss carry-back claims all require preparation before lodgement.
Frequently Asked Questions
Does permanent IAWO help IT contractors?
Yes, for hardware under $20,000 each (laptops, monitors, servers, networking gear, dev boards). For more expensive items (workstations over $20k, multi-GPU rigs), standard depreciation pool rules apply. The permanent designation removes annual sunset uncertainty, so you can plan hardware refresh cycles across multiple years without worrying about write-off availability.
Should IT contractors operate as sole trader or company?
It depends on income level, PSI status, asset protection needs, and partner or family situation. The new loss carry-back applies to companies only, and the trust 30% minimum tax from 2028 may push contractors away from trust structures. The right answer is personal, so model it with your accountant using your actual numbers.
Does ATO PSI affect Budget changes?
PSI rules continue unchanged. If your IT contracting income is PSI, deductions are restricted to those an employee could claim. PSI isn't labour income for the new $1,000 standard deduction, so the $1,000 only applies to a salary or director fees you pay yourself. Continued ATO compliance funding means incorrect PSI classification is still a real review risk.
Will payday super affect a single-person contracting company?
If you draw a wage from your company, even just yourself as the sole director, you are an employee for super purposes, and payday super applies from 1 July 2026. If you only take dividends and draw no salary, there are no super obligations triggered by payday super. The structure of how you take money out of your company matters.
Are R&D incentives changing for IT contractors?
The Budget announced R&D Tax Incentive changes that start on 1 July 2028: core R&D offset rates rise by 4.5 percentage points, supporting R&D stops being eligible, and the minimum expenditure threshold rises from $20,000 to $50,000. FY2026-27 claims use the existing rules, so check ATO guidance before lodgement rather than assuming the new settings apply.
Does the $1,000 flat deduction work for contractors?
Only for wage or director income. The flat $1,000 applies to labour income such as a salary or director fees your own company pays you; PSI and other contracting income don't count. Business deductions are claimed separately on the business schedule and don't reduce the $1,000.
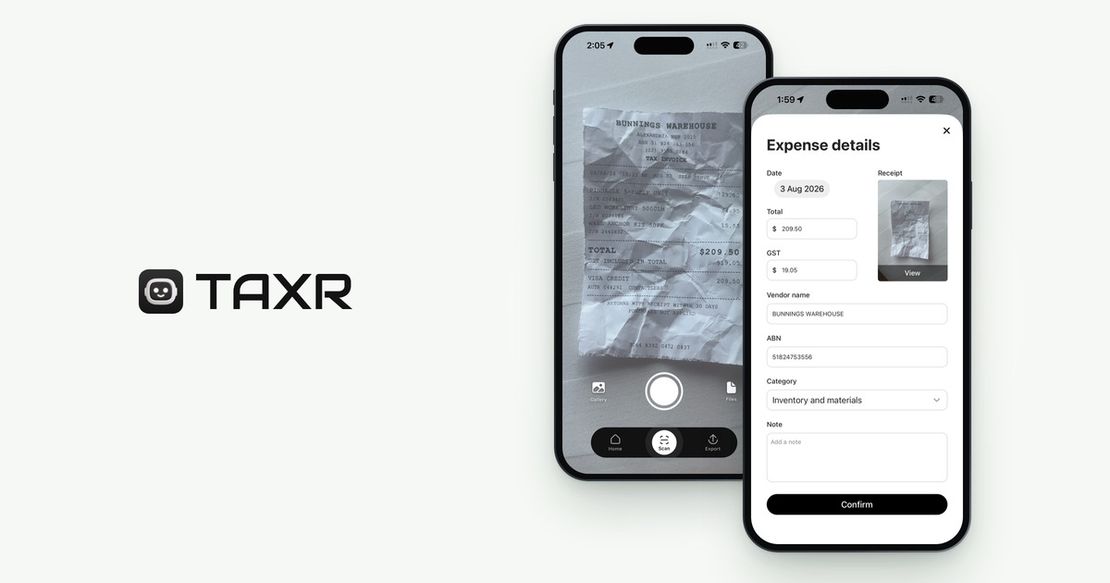
IT contractors lose deductions to forgotten subscription receipts, uninvoiced SaaS renewals, and hardware purchases buried in a bank feed more than to any Budget change. Taxr captures every receipt the moment it lands: import SaaS invoices as PDFs, scan physical receipts with the camera, and get a category suggested for each one, so your hardware, software and professional development costs are already sorted when your accountant asks. Download Taxr and stop manually tagging Stripe receipts in Gmail.