The New $1,000 Flat Tax Deduction: Who Qualifies
Table of Contents
In short: Australia's $1,000 flat deduction for work-related expenses applies from the 2026-27 income year (from 1 July 2026), needs no receipts and has been law since June 2026. It goes to Australian residents for tax purposes who earn assessable labour income, such as salary and wages, director fees or parental leave pay. Sole traders who only earn business income aren't eligible.
Australia's $1,000 flat tax deduction landed in the 2026-27 Federal Budget delivered on 12 May 2026, and it is one of the most practically significant changes for working Australians in years. From 1 July 2026, eligible workers get a flat $1,000 work-related deduction with no receipts required, instead of itemising individual expenses. If you earn a salary or wages, this change almost certainly affects you. If you only earn business income as a sole trader, it doesn't apply to you (more on that below).
Here is exactly what it means, who qualifies and, critically, when you should still be keeping those receipts.
Disclaimer: This article provides general information only and does not constitute tax advice. Consult a registered tax agent for advice specific to your circumstances.
What the New $1,000 Deduction Actually Is
According to Budget Paper No. 2 (2026-27), the Government is introducing a $1,000 standard deduction for work-related expenses available to all eligible Australian workers from the 2026-27 income year. It became law in June 2026 in the Treasury Laws Amendment (Tax Reform No. 1) Act 2026. Rather than gathering receipts, tracking expenses and calculating a total, you can let the ATO apply the flat $1,000 automatically and move on. Treasury estimates this will benefit approximately 6.2 million workers, with an average saving of around $205 per person, though the actual saving depends on your individual marginal tax rate.
The mechanism is simple. If you're eligible, the ATO applies the $1,000 automatically, and any work-related expenses you claim reduce it dollar for dollar. So each year you decide whether to claim your actual work-related expenses, backed by records, or leave them off and take the $1,000. You cannot combine both: claim $600 of expenses and your standard deduction drops to $400; claim more than $1,000 and it drops to nil. This is worth stressing because one of the most common mistakes will be people expecting the flat $1,000 on top of itemised expenses.
Importantly, the deduction covers work-related expenses: the spending employees claim on their individual income tax return. Think tools, uniforms, professional development, work-from-home costs, phone and internet. It does not replace business deductions, which sole traders claim in the business section of their return, and union fees, professional memberships, donations and investment-related claims are still claimed on top. The ATO's existing framework for what constitutes a deductible work-related expense still governs what you can itemise.
Who Qualifies
The flat $1,000 deduction is broad: Treasury expects around 6.2 million Australian workers to benefit. You're eligible if you are an Australian resident for tax purposes and earn assessable labour income, such as salary and wages, director fees or parental leave pay. Full-time, part-time and casual employees all qualify, including those running a freelance practice on the side. Business income doesn't count: a sole trader or contractor who only earns business income isn't eligible. You also don't need to have spent the $1,000 to receive it.
The deduction is available from the FY2026-27 return, that is, the return covering 1 July 2026 to 30 June 2027, which you will lodge from July 2027 (or later through a registered tax agent). It does not apply retrospectively to your 2025-26 return.
For wage earners who have previously found the paperwork of itemising overwhelming, including those with a freelance side business, this is a genuine simplification. If your annual work-related spending sits below $1,000 (perhaps you work mostly from an employer-supplied setup with minimal personal expenses), the flat deduction may actually produce a larger claim than itemising. If you are in this category and want a sense of where you typically land, our sole trader tax calculator can help you model the difference. For a deeper look at what individual deductions you might be entitled to, see our guide to tax deductions for freelancers.
How to Decide: Flat $1,000 or Itemise?
Every year from FY2026-27 onward, you will face a choice. Here is how to think through it.
When the flat $1,000 wins
The flat $1,000 makes sense when your genuine work-related expenses are below $1,000, or close to it and you do not have reliable records. It also wins when your expenses are real but scattered and time-consuming to substantiate. Low work-from-home workers, employees in client-supplied environments, and people in straightforward salaried roles with minimal job-specific spending are the clearest beneficiaries. If you would normally claim $300 to $700 in work-related items, the flat $1,000 is an automatic improvement with zero effort.
For a full breakdown of how the two approaches compare across different expense profiles, see our flat $1,000 vs itemise comparison post.
When itemising wins
Itemising beats the flat $1,000 the moment your genuine, substantiated work-related expenses exceed $1,000. This threshold is surprisingly easy to cross. Heavy work-from-home users claiming under the ATO's 70-cents-per-hour fixed rate can accumulate several hundred dollars in home office expenses alone. Add a vehicle logbook, professional development courses, professional indemnity insurance and equipment depreciation, and you are well past $1,000 before June.
If you claim any of the following regularly, run the numbers before defaulting to the flat deduction:
- Work-from-home hours (fixed rate method, 70c/hour for 2025-26, or actual cost method)
- Vehicle use with a logbook
- Professional development: courses, conferences, certifications, publications
- Equipment depreciation: laptops, cameras, tools costing over $300
- Professional memberships and union fees (claimed on top of the $1,000 either way, so keep these receipts regardless)
- Income protection insurance premiums (also claimed on top of the $1,000)
For a detailed list of what falls into each category and how to record it, our 17 deductions Australian freelancers miss covers the most commonly overlooked claims. There is also a practical step-by-step walkthrough for making the most of either approach in our guide to claiming the $1,000 flat deduction.
What Records You Still Need
For the standard deduction itself, "no receipts required" is literally true: the ATO says you get it without needing to have spent the money or kept records. Records still matter for everything else. Union fees, professional memberships, donations and tax agent fees are claimed on top and need records, and if you claim work-related expenses instead of taking the $1,000, you need written evidence for all of them, because the $300 no-receipt limit ends on 1 July 2026.
The practical implication: keep scanning receipts anyway. The ATO's data-matching programme is extensive, covering bank transactions, digital payments, and expense categories across most industries. If an itemised claim looks implausible against your income type and the ATO's benchmarks, an audit notice can arrive.
Keeping receipts also gives you optionality. You only discover at the end of the year whether your total exceeds $1,000, and by then, if you have not been recording, it is too late to switch to itemising. Scan as you go, let the total accumulate, and choose at lodgement time. That is the only way to guarantee you always pick the larger deduction.
Interaction with Other Budget Changes
The $1,000 flat deduction does not sit in isolation. The 2026-27 year also brings the already-legislated tax cut that reduces the 16% marginal tax rate to 15% from 1 July 2026. For average-income earners, the combination of a lower marginal rate and the flat deduction simplification means both a smaller tax bill and less paperwork: a meaningful double benefit for workers who have neither complex finances nor the time to engage deeply with the tax system each year.
The interaction matters for calculation: the tax saving from a $1,000 deduction is $150 at the new 15% rate, $300 at 30%, $370 at 37% and $450 at 45%, plus another $20 where the 2% Medicare levy applies. Treasury's headline figure of approximately $205 per worker reflects the spread across all eligible workers at different income levels.
Common Mistakes to Avoid
A few traps are predictable from the way this deduction will be marketed and misunderstood.
Stacking the flat $1,000 with itemised expenses. You cannot get both. Work-related expenses you claim reduce the $1,000 dollar for dollar, so you end up with the larger of the two, never the sum.
Claiming for non-work expenses. The flat $1,000 still only covers work-related expenses. It does not open the door to claiming personal spending. The ATO's definition of "work-related" has not changed, so the rules for anything you itemise are the same as before.
Skipping records entirely. The standard deduction needs no records, but almost everything else does. Union fees, professional memberships, donations and tax agent fees are claimed on top and need records, and if you claim work-related expenses instead of the $1,000, you need written evidence for every one of them now that the $300 no-receipt limit has gone.
Assuming $1,000 is always the right choice. Run the comparison every year. Your expenses vary. A year with significant professional development spending or equipment purchases could push your itemised total well past $1,000, which makes records from that year genuinely valuable.
Frequently Asked Questions
When does the $1,000 flat tax deduction start?
From 1 July 2026, which is the beginning of FY2026-27. The deduction first appears on returns lodged for that financial year, so the earliest most people will use it is from July 2027, when FY2026-27 returns open. It does not apply to your 2025-26 return.
Do I need any receipts for the flat $1,000 deduction?
No. If you're eligible, the ATO applies the $1,000 automatically, and you don't need receipts or even to have spent the money. You only need records for the work-related expenses you choose to claim yourself, and for deductions claimed on top, such as union fees and donations.
Can sole traders use the $1,000 flat deduction?
Only if you also earn labour income. The deduction applies to assessable labour income such as salary and wages, director fees and parental leave pay, so a sole trader who only earns business income isn't eligible. A sole trader who also has a wage job gets it against that labour income. Business deductions are claimed in the usual way in the business section of the return and don't reduce the $1,000.
Is $1,000 always better than itemising?
No. The $1,000 is a floor, not a ceiling. If your genuine work-related expenses exceed $1,000 and you have the records to support them, itemising will always produce a larger deduction and a lower tax bill. The flat $1,000 is most valuable for people whose actual expenses are below that threshold, or who lack documentation to substantiate a higher claim.
How much tax does $1,000 actually save me?
It depends on your marginal rate. A $1,000 deduction reduces your taxable income by $1,000, so the tax saving is that amount multiplied by your marginal rate. At the new 15% rate: $150. At 30%: $300, or $320 including the 2% Medicare levy. Treasury's headline saving of approximately $205 per eligible worker reflects the average across all income levels in the eligible group; your result will be higher or lower depending on where your income sits.
Does this replace the $300 "no receipts" rule?
In effect, yes. From 1 July 2026 the ATO no longer applies the $300 limit for claiming work-related expenses without written evidence (the $150 laundry limit and the award transport exemption also go). If you claim more than the standard deduction, you need written evidence for every work-related expense you claim.
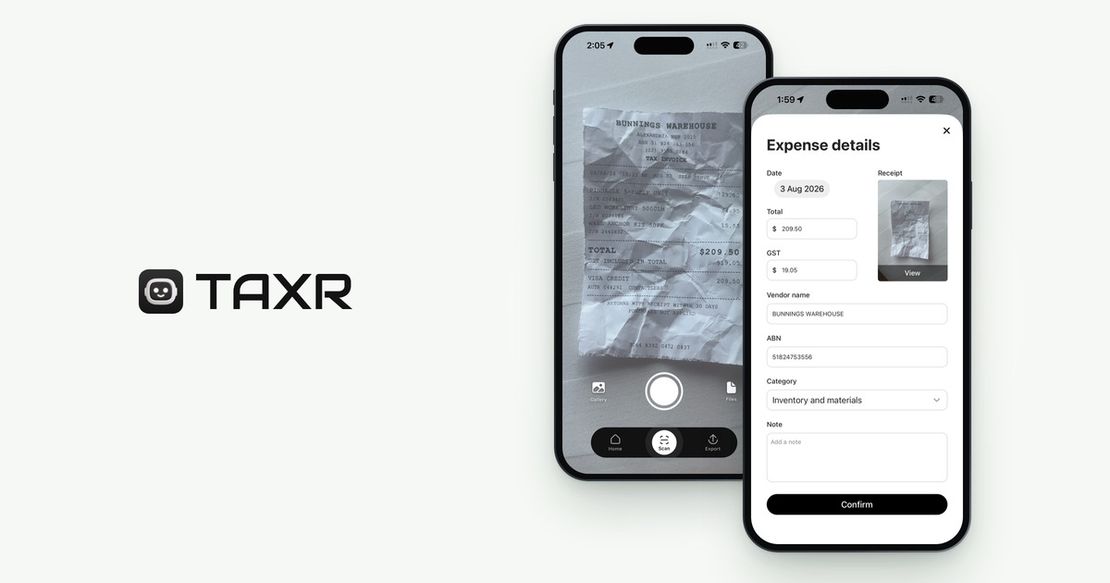
Taxr makes the flat-or-itemise decision easy. Scan every receipt the moment it lands and the app totals your expenses by category as you go. When tax time arrives, you can see straight away whether your itemised claim beats $1,000, and if it does, your records are already organised and ready. If the flat deduction wins, you still have clean records for the deductions you claim on top.
Download Taxr now and go through 2026-27 knowing you will always claim the larger deduction.